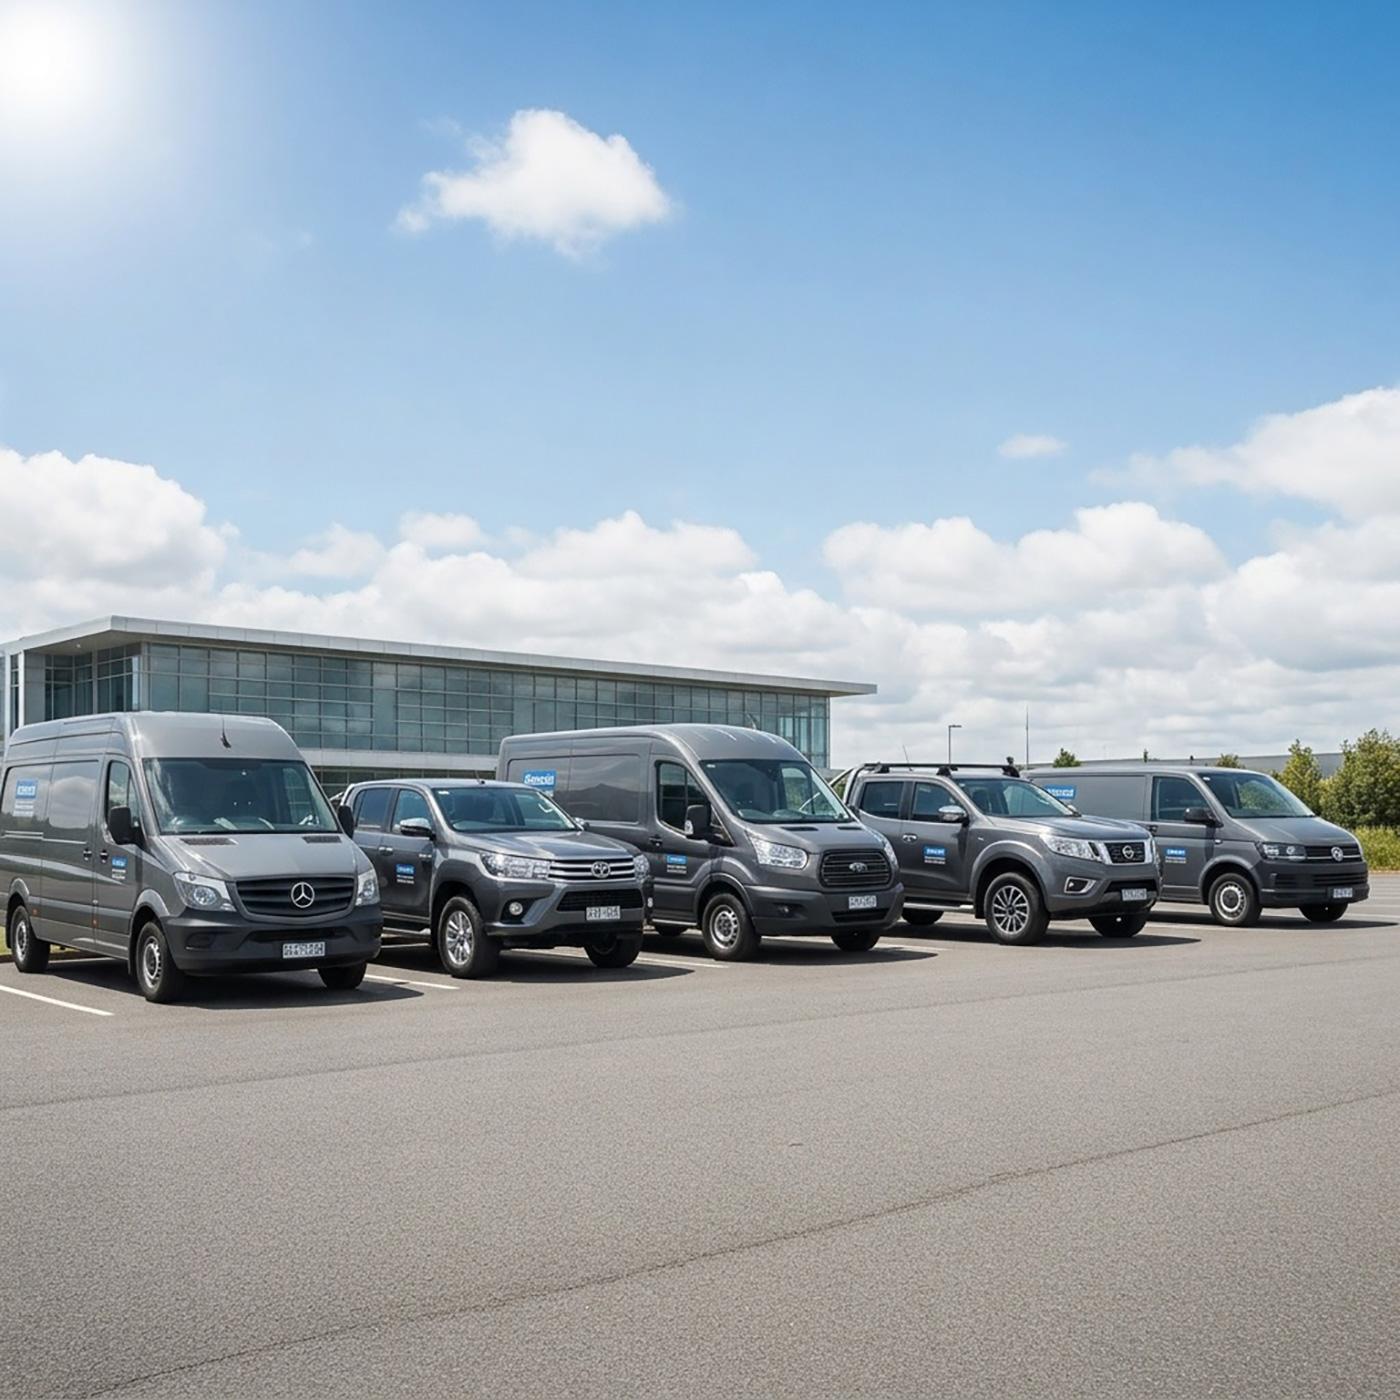
Is leasing right for your next small business vehicle?
For a small business, a vehicle is often much more than transport. It may carry tools, deliver products, take employees to customers or keep essential services running. When a vehicle is unavailable, the impact can quickly flow through to your team and customers.
Leasing can give New Zealand businesses a practical way to access reliable vehicles, manage costs and reduce the time spent on administration.
Whether it’s the right choice depends on what you need the vehicle to do, how your business uses its capital and how much support you want managing it.
Seb AlpeSME Sales Manager, ANZ
06 Oct 20264 min read
Start with what your business needs from the vehicle
Before comparing finance options, consider the role the vehicle will perform.
Think about daily distances, passenger numbers, carrying capacity, equipment, towing requirements and the roads and conditions it will encounter. If you’re considering an electric vehicle, access to charging and typical travel patterns will also be important.
The purchase price or lease repayment is only part of the equation. Fuel or electricity, maintenance, tyres, insurance, Road User Charges, downtime and disposal can all affect the whole-of-life cost.
Starting with your operational needs can help you choose a vehicle that provides long-term value, rather than simply the lowest upfront price.
Could leasing protect your working capital?
Buying a vehicle outright can use funds that might otherwise support stock, recruitment, equipment, technology or new business opportunities. Financing a purchase may spread the cost but can still require a deposit and use borrowing capacity.
Leasing generally requires less capital upfront, allowing your business to pay for the use of the vehicle over an agreed term. This can provide greater financial flexibility, particularly when you’re adding vehicles to support new employees, customers or contracts.
How predictable would your vehicle costs be?
Regular lease repayments can make finance costs easier to plan for. With a fully maintained lease, selected operating expenses may also be incorporated into one regular payment.
Depending on the arrangement, this could include scheduled servicing, tyres, registration, Warrant of Fitness or Certificate of Fitness requirements, Road User Charges and roadside assistance.
Not every expense will necessarily remain fixed throughout the lease. You'll need to decide what you want to include, and understand how operating budgets are reviewed and whether adjustments may apply.
How much time do you spend managing vehicles?
Even a small fleet can create a steady flow of maintenance tasks, invoices and renewal dates. For an owner or small team, that work competes with other business priorities.
Maintenance management can give drivers access to an approved service network while specialists coordinate servicing, repair approvals and tyre replacement. Depending on the services selected, a fleet management provider may also help manage:
Vehicle registration
Warrant of Fitness and Certificate of Fitness requirements
Road User Charges
Fuel
Tolls and infringements
Insurance and accident management
Vehicle reporting and record keeping
Bringing these activities together can reduce administration, support vehicle reliability and provide a clearer view of costs and upcoming requirements.
What could leasing mean for safety and compliance?
When employees drive for work, their vehicles form part of the workplace. Businesses need to consider vehicle condition, driver safety and the risks associated with work-related travel.
A planned leasing and replacement cycle can provide access to newer vehicles with current safety technology. Scheduled maintenance, compliance support, driver training and telematics can provide further insight into vehicle condition and use.
The right approach will depend on where your employees drive, the distances involved, the loads they carry and the conditions they encounter.
Will the arrangement adapt as your business changes?
The vehicle that suits your business today may not be the same in 3-5 years. Your workload, service area, employee numbers or environmental goals may change over time.
Leasing can create a planned pathway for replacing vehicles as your needs evolve. However, a lease is still a commitment for an agreed period, so it’s important to choose the term, kilometre allowance and vehicle specifications carefully.
You should also understand the end-of-lease requirements, including provisions relating to vehicle condition, kilometres and any modifications.
What might this look like for a growing business?
Consider whether you'll need to add another vehicle to support a new employee. Purchasing could use capital needed for tools, training and other start-up costs associated with the role.
A fully maintained lease could spread the vehicle cost while providing support with maintenance and administration.
However, purchasing may offer better value if the business expects to keep the van for many years or needs to make extensive specialised modifications.
The better option depends on the full operating picture, not simply the monthly repayment.
What are the tax considerations?
Businesses may be able to claim vehicle expenses to the extent that a vehicle is used for business purposes. The treatment will depend on your business structure, GST registration and any private use of the vehicle.
Whichever option you choose, compare the upfront and whole-of-life costs, operational support, flexibility and end-of-term position.
Custom Fleet can help you assess different leasing and fleet management options based on how your vehicles operate, your available budget and your future plans.
Recent articles
Find the right approach for your business vehicles
Talk to our SME team about a practical vehicle solution for your New Zealand business.